Choosing between high-growth software leaders often involves balancing rapid expansion against proven profitability. We compare the collaborative design innovator Figma (FIG -6.35%) and the enterprise workflow powerhouse ServiceNow (NOW -4.56%) to see which is a better buy.
Figma provides a collaborative canvas where teams build digital products together, while ServiceNow offers a platform that automates work across IT, HR, and customer service departments. Both companies are currently integrating artificial intelligence to help their enterprise customers work more efficiently, though they occupy very different stages of financial maturity.
The case for Figma
Figma sells a cloud-based design platform that connects design, code, and AI in a single collaborative space. The company serves a diverse user base of designers and developers, utilizing a self-service model alongside enterprisewide sales for large organizations. To drive further growth, the company introduced new pricing and billing structures in 2025 and launched AI credits in March 2026. While Figma has historically grown through word-of-mouth, it is now focusing heavily on enterprise procurement processes to capture larger clients within the tech stocks category.
In its 2025 fiscal year (FY), revenue reached $1.1 billion, representing a significant revenue growth of 41% compared to the previous year. Despite this top-line expansion, the company reported a net loss of approximately $1.3 billion for the same period. This reflects a net margin of negative 118.4%, which shows that expenses currently far exceed the revenue generated. This trend of widening losses suggests a company still prioritizing aggressive market capture and product development over immediate bottom-line results.
Figma maintains a healthy balance sheet with a debt-to-equity ratio of 0.1x as of December 2025. This ratio, which compares total debt to the equity owned by shareholders, suggests a very low reliance on borrowed money. The current ratio, which measures the ability to cover debts due within one year, is strong at 2.6x. The company generated free cash flow of $246.2 million in FY 2025. However, note that stock-based compensation represented 544.2% of operating cash flow, meaning reported cash generation is heavily inflated by this non-cash add-back.
The case for ServiceNow
ServiceNow provides an AI-powered platform designed to connect workflows and data across massive organizations. The company serves thousands of enterprise customers, including hundreds of clients that spend more than $5 million annually. It reaches these customers through a robust partner ecosystem that includes global integrators like Accenture (ACN +1.71%) and strategic technology partners such as Microsoft (MSFT -1.88%) and NVIDIA (NVDA -1.06%). Recent acquisitions, including the 2026 purchases of Pyramid Analytics and Armis, aim to expand its capabilities in analytics and security asset visibility.
In FY 2025, revenue reached $13.3 billion, a year-over-year revenue growth of 20.9%. Unlike many high-growth software companies, ServiceNow is consistently profitable, reporting net income of $1.7 billion during that same fiscal period. This resulted in a net margin of 13.2%, which is consistent with its performance in recent years. The company has successfully scaled its operations while maintaining a double-digit percentage of revenue as bottom-line profit.
As of its December 2025 balance sheet, the company carries a debt-to-equity ratio of approximately 0.2x. This indicates a conservative capital structure where debt is low relative to shareholder equity. The current ratio stands at 1.0x, suggesting the company has just enough short-term assets to cover its immediate liabilities. ServiceNow generated impressive free cash flow of $4.6 billion in FY 2025. Note that stock-based compensation represented 35.9% of operating cash flow.
NOW & FIG: Performance Comparison
Key Financial Metrics


Risk profile comparison
Figma faces intense competitive threats from established giants like Adobe (ADBE -2.93%) and newer AI-driven design tools. The company also deals with risks related to rapid AI evolution, including a reliance on third-party models and the potential for inaccurate or biased generated content. Operational security is another concern, as complex AI workflows can be vulnerable to data leakage. Additionally, Figma is navigating an ongoing inquiry by the Office of Foreign Assets Control regarding potential past sanctions violations, which adds a layer of regulatory uncertainty to its business.
ServiceNow operates in a rapidly evolving market where it must compete with AI-native vendors and traditional enterprise software providers like Salesforce (CRM -2.12%), Oracle (ORCL -4.42%), and SAP (SAP -0.64%). The company faces potential pricing pressure and implementation delays due to the increasing complexity of large enterprise deals. Regulatory risks are also present, as the company is currently cooperating with a Department of Justice investigation regarding certain government contracting matters. Furthermore, integrating major acquisitions like Armis carries the risk of operational disruption if the transition is not seamless.
Valuation comparison
ServiceNow appears to be the more conservatively valued option based on future earnings estimates, while Figma carries a higher premium reflecting its faster revenue growth rate.
| Metric | Figma | ServiceNow |
|---|---|---|
| Forward P/E | 78.7x | 36.3x |
| P/S ratio | 9.2x | 10.4x |
Valuation metrics include sourcing from Financial Modeling Prep (FMP) and may differ from other data providers.
The P/S ratio measures market value against sales over the past twelve months. The Forward P/E compares the current stock price to future earnings estimates over the next year.
Which stock would I buy in 2026?
Weighing an investment in Figma or ServiceNow is a choice between a high-growth, newly public design disruptor and a massive, highly profitable enterprise workflow titan. Figma could deliver outsized share price returns, since it is the newer software player. ServiceNow is the more conservative bet, but its profitable business offers stability.
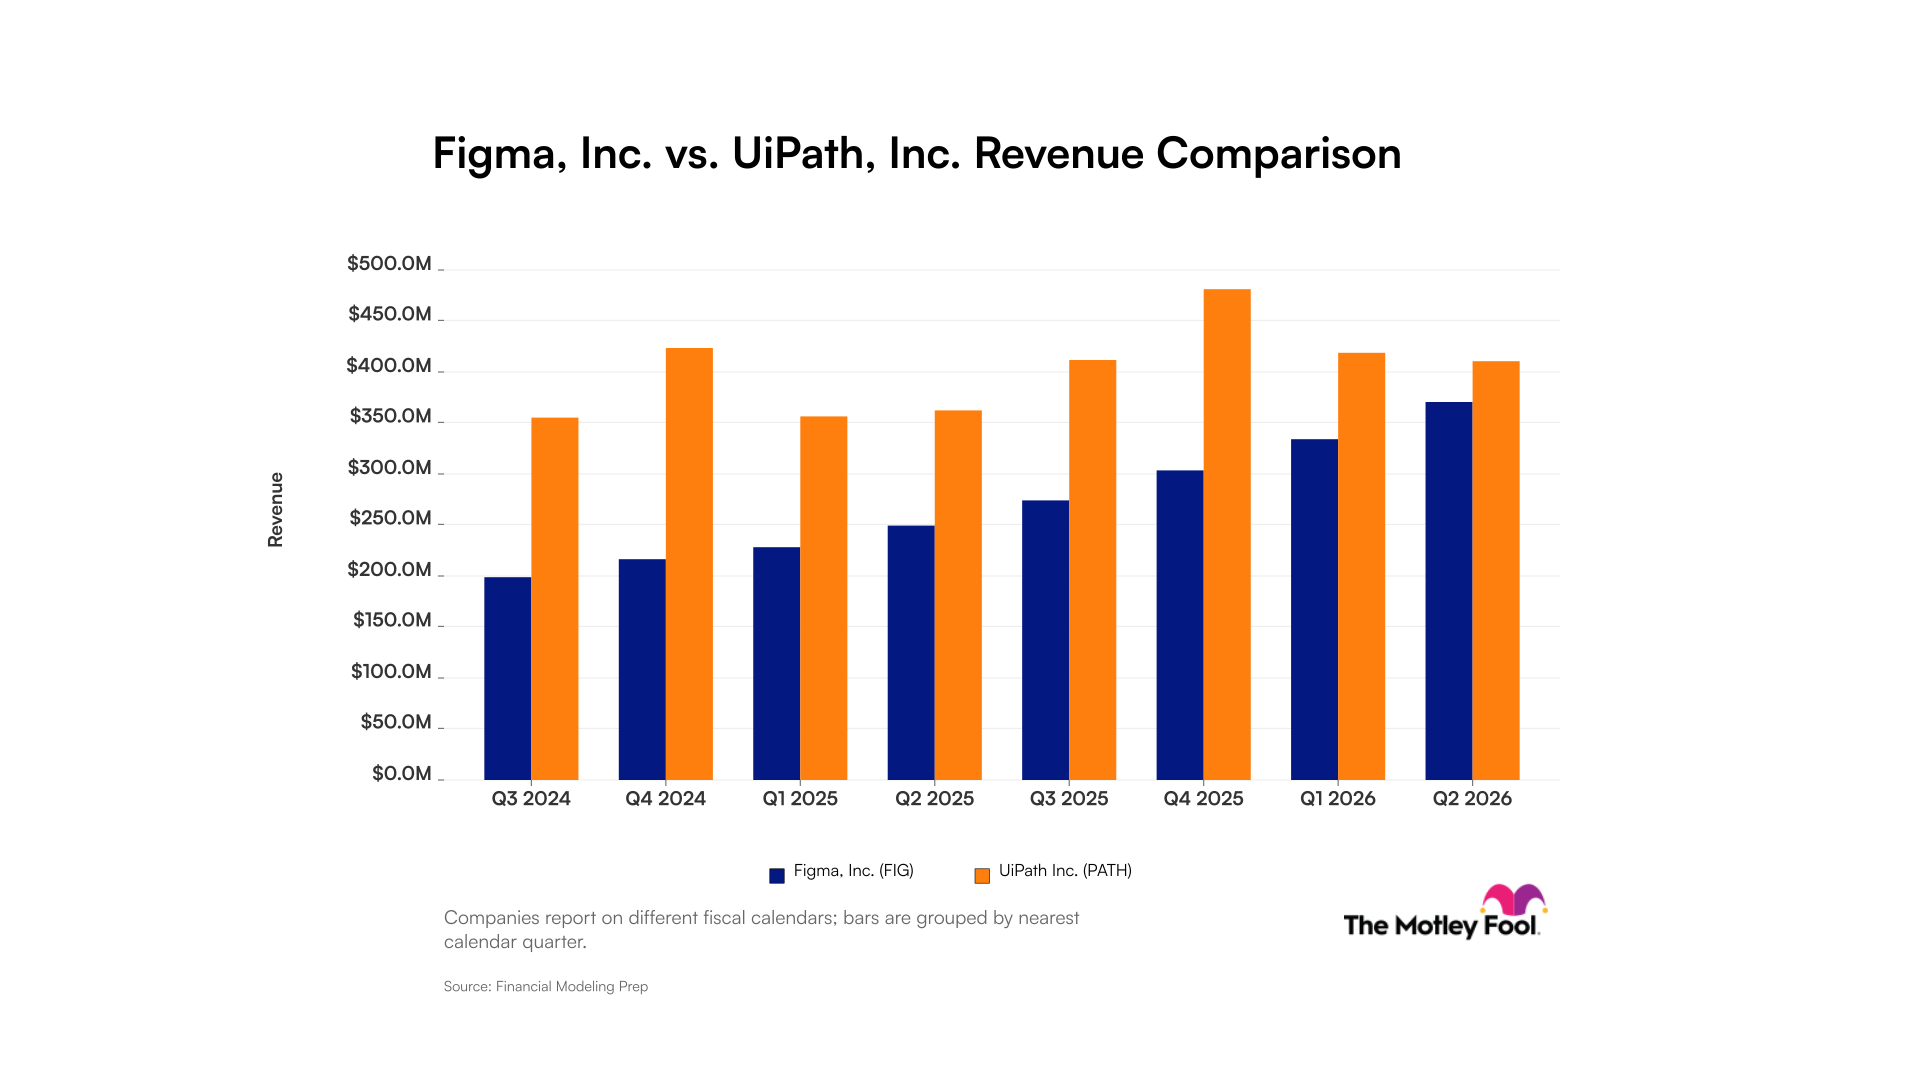
Between the two, I would pick ServiceNow. That said, I like Figma's growth rate. In the second quarter, sales hit $370.1 million, a record high and an outstanding 48% year-over-year increase. This was the first full quarter of AI credit monetization, suggesting its AI offerings are gaining traction with customers and producing a new revenue stream.
However, that AI-driven sales growth came with an enormous cost increase. Figma's Q2 bottom line swung from net income of $28.2 million in 2025 to a net loss of $112.2 million in 2026. This injects uncertainty around the company's ability to drive toward profitable sales growth.
Meanwhile, ServiceNow continues to deliver excellent results. The company's second-quarter revenue of $4 billion represented a 24% year-over-year increase. Moreover, its AI agentic deployments rose ninefold in nine months, demonstrating that customers are embracing the new AI functionality while ServiceNow remained profitable with Q2 net income of $298 million.