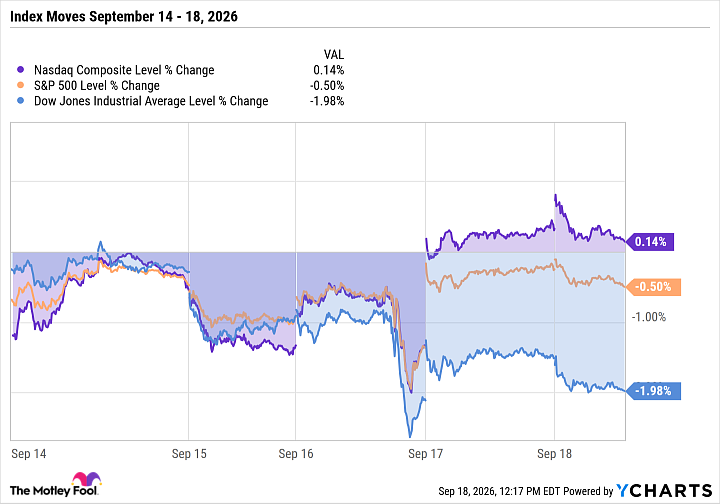
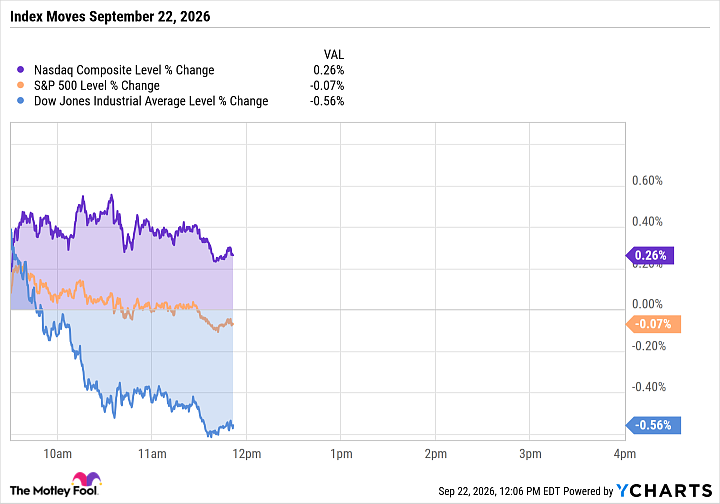
The major market indexes displayed their differences on Tuesday morning. The Nasdaq Composite (^IXIC +0.48%) rose 0.3% as of 12:06 p.m. ET. Meanwhile, the Dow Jones Industrial Average (^DJI +0.93%) fell 0.6%. Between these extremes, the S&P 500 (^GSPC +0.51%) essentially stayed flat with a 0.1% drop. The Nasdaq index set a fresh intraday high at 10:35 a.m. ET.
Memory chips rose while banks fell
The Dow's problem was every financial stock, all at once. JPMorgan Chase (JPM +1.33%) fell 3.5% and took out 72 Dow points. Travelers (TRV +0.18%) dropped 2.8% for another 62 points, and Visa's (V -0.16%) 2.4% dip accounted for 53 Dow points. Altogether, financial stocks took 286 points off the index. Try as I might, I found no company-specific news to explain any of it.
That suggests a gloomy day for macroeconomics, but I'm still looking for evidence of that. Oil prices are down as Iran set up a framework to maybe, perhaps, possibly reopen the Strait of Hormuz within a week. There's also progress on reopening the damaged East-West pipeline in Saudi Arabia. Still, large energy stocks barely moved on the news.
Image source: Getty Images.
I can't point to rising Treasury yields, either. Both long- and short-term bonds saw their yields slide slightly lower today.
As for the cap-weighted indexes, nothing is moving their scores by at least 0.1% (my personal threshold for analysis in this series). It's as if Wall Street is holding its breath, waiting for something big. It can't be the United Nations summit, which is already underway. Hold that thought.
The Nasdaq Composite is up for a reason, though. Memory stocks rose this morning, led by a 6.5% gain for Sandisk (SNDK +1.38%) and a 3.6% jump in Micron Technology (MU +0.16%) prices. Sandisk got a bullish analyst note and joined the S&P 100 (XEO +0.53%) index yesterday. Micron investors are prepping for next week's Q4 2026 earnings report.
Dow Jones Industrial Average
Key Data Points
The record comes with a caveat
I don't know about "all eyes," but I'm certainly watching Thursday's meeting between Donald Trump and Xi Jinping. Nothing else seems to explain the market's quiet mood today. The meeting should touch on market-moving topics such as AI policies, tariff rates, rare-earth metals trades, and the Iranian conflict.
So there's a record high in one index, a 286-point hole in another, and very little news behind either move. You can cut the tension with a memory stick, or maybe an oil drill.