Nvidia (NVDA +0.97%) CEO Jensen Huang has never been shy about making bold predictions for artificial intelligence. And he's sticking with one of his biggest: that global AI infrastructure spending could reach $3 trillion to $4 trillion by 2030. That's an extraordinary amount of money, even for an industry where the biggest players are already spending hundreds of billions of dollars a year on building data centers and expanding computing capacity.
But there's an important distinction for investors. Huang isn't predicting that Nvidia will generate trillions of dollars in revenue. He's describing the potential size of the infrastructure build-out that could support the next generation of AI applications.
So, with expectations already running high and Nvidia stock recently hitting a new all-time high, is the stock still worth buying?
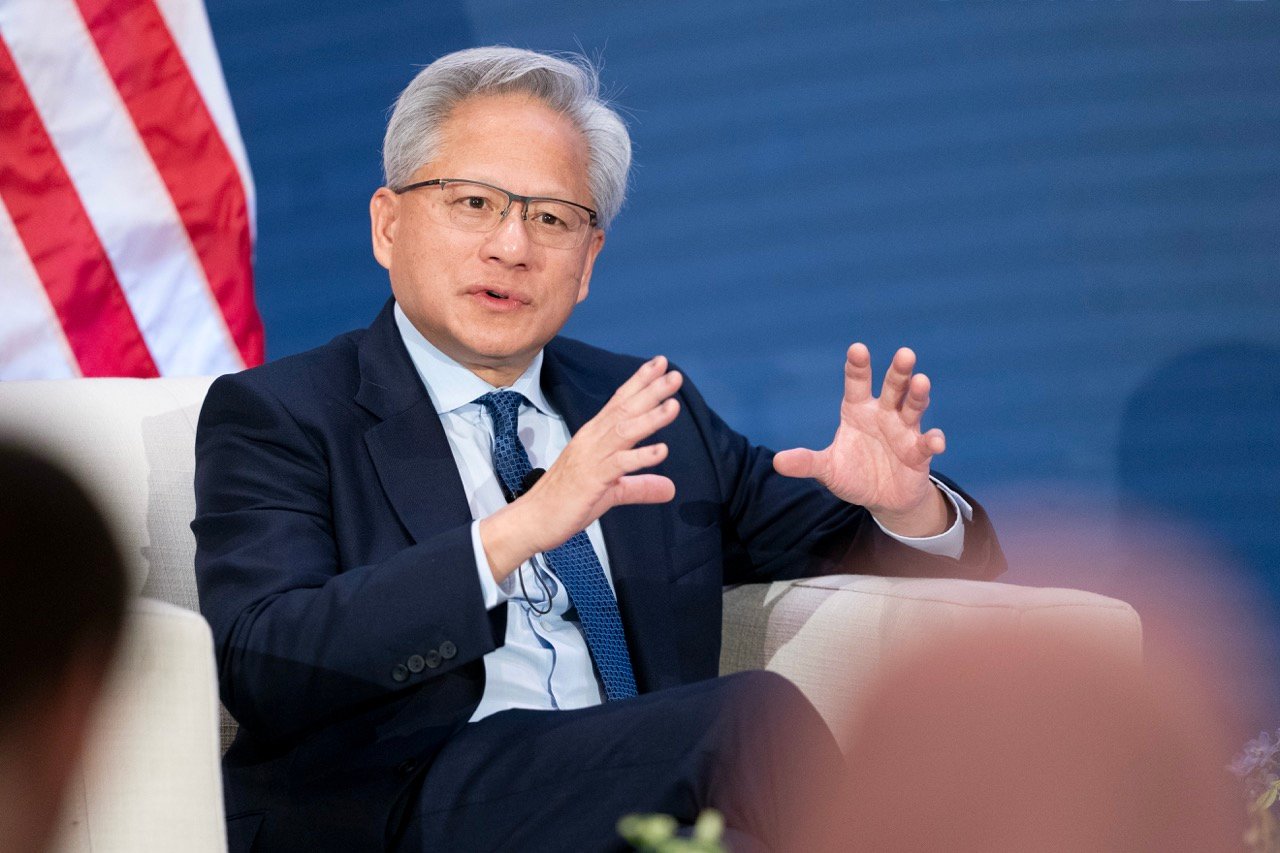
Nvidia CEO Jensen Huang. Image source: Getty Images.
Nvidia has more than one way to benefit
Nvidia's biggest advantage isn't simply that it makes powerful graphics processing units (GPUs). The company also supplies networking equipment, central processing units (CPUs), and software that help its customers build and operate AI data centers. That diverse portfolio allows Nvidia to capture a larger share of infrastructure spending than it could by selling GPUs alone.
Its new Vera Rubin architecture combines Vera CPUs, Rubin GPUs, high bandwidth memory, and high-speed connections designed to move information between processors and servers efficiently. Nvidia says the platform can improve the performance and efficiency of large AI systems. And those are two factors that matter enormously to companies spending vast sums on computing capacity.
Nvidia isn't standing still. The company is developing new chip architectures and integrated systems at an accelerated cadence, giving customers reasons to upgrade their equipment regularly as AI models become more demanding.

NASDAQ: NVDA
Key Data Points
Could Nvidia fall short?
Of course, Huang's forecast is a prediction, not a guarantee. And investors shouldn't assume Nvidia will capture any specific fixed percentage of the dollars being spent on AI infrastructure.
Advanced Micro Devices and Cerebras Systems are competing with Nvidia for a slice of the GPU business, while major cloud providers and large AI labs are partnering with specialist chip designers to develop custom AI processors that could reduce their dependence on Nvidia hardware for certain types of workloads. Amazon and Alphabet are among the hyperscalers that have developed their own processors, and they're continuing to refine those designs.
There's also the question of whether companies investing heavily in AI will generate enough profit to justify that spending. If returns on investment disappoint, data center expansion could slow. That's a legitimate concern, particularly for a company whose customers are making enormous investments based partly on their expectations of future demand for compute. It's one of the reasons why I've labeled this the "show me" phase of the AI build-out.
Why Nvidia stock is still a buy
I think Nvidia remains a compelling long-term investment, even if Huang's $3 trillion to $4 trillion forecast proves too optimistic.
The company has established itself as a major supplier of the hardware and systems needed to build AI infrastructure, and its expanding product portfolio offers several avenues for continued spending.
Investors still need to consider the stock's valuation. But I wouldn't bet against Nvidia simply because its fastest growth years might be behind it. The AI infrastructure build-out has a long way to go.